Alkaline electrolyzers lead by technology, PEM is set to grow fastest, and Asia-Pacific dominates deployment and manufacturing as low-emissions hydrogen scales up
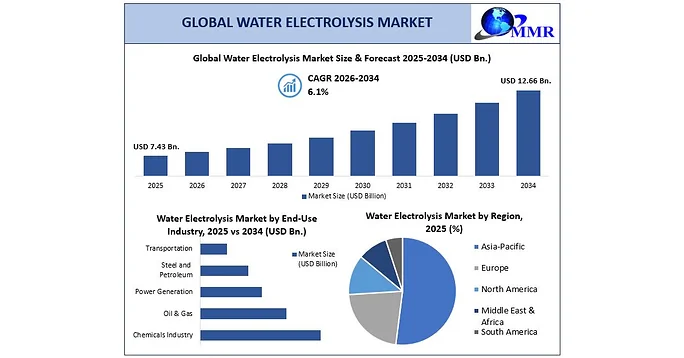
PUNE, India, Oct. 1, 2026 /PRNewswire/ -- The global Water Electrolysis Market was valued at USD 7.43 billion in 2025 and is projected to reach USD 12.66 billion by 2034, growing at a CAGR of 6.1% during 2026–2034, according to a new report by MMR. The study points to a market moving from an emerging clean-hydrogen technology toward a broader industrial equipment market.
Global Water Electrolysis Market
The Global Water Electrolysis Market Report 2025 provides a detailed analysis of market trends, low-emissions hydrogen demand, electrolyzer technologies, industrial feedstock applications, renewable energy integration, competitive strategies, and forecasts through 2034. Water electrolysis is a hydrogen-production process in which electricity is used to split water into hydrogen and oxygen through an electrolyzer. It is particularly important for producing low-emissions hydrogen when the power comes from renewable or nuclear sources. Key technologies include Alkaline Electrolysis, Proton Exchange Membrane (PEM) Electrolysis, Solid Oxide Electrolysis, and Anion Exchange Membrane (AEM) Electrolyzers. Demand is increasing across refining, ammonia, methanol, steel, power generation, energy storage, sustainable fuels, and transportation as industries look to cut emissions from hydrogen production.
The Global Water Electrolysis Market was valued at USD 7.43 billion in 2025 and is projected to reach USD 12.66 billion by 2034, growing at a CAGR of 6.1% during 2026-2034. Growth is supported by rising hydrogen requirements, government support for clean hydrogen, falling equipment costs, and a larger pipeline of electrolysis projects. Global installed electrolysis capacity more than doubled in 2025 to above 4 GW, with more than 2.5 GW under construction. Alkaline electrolysis remained the largest technology segment because of its commercial maturity, lower capital requirements, and suitability for large-scale production, while PEM is expected to grow faster on its compact design and ability to work with variable solar and wind power. Industrial Feedstock was the leading application segment, and Asia-Pacific led the market, with China accounting for nearly three-quarters of new electrolysis installations in 2025.
A major shift in the Water Electrolysis Market is the move from small demonstration projects to larger commercial installations, along with a push for lower costs, higher efficiency, and regional manufacturing. Nel ASA entered a framework agreement with Hydrasun in September 2026 to build European assembly and integration capabilities for its modular PEM electrolyzers. thyssenkrupp nucera and BHEL signed a collaboration in July 2026 to localize alkaline electrolyzer module fabrication in India. BASF commissioned Germany's largest green hydrogen production facility at Ludwigshafen in May 2026 using Siemens Energy PEM technology. ITM Power also received approval for a £46.5 million UK government grant in July 2026 to support its Chronos electrolyzer manufacturing capability. These developments reflect the industry's broader move toward scalable, cost-efficient electrolysis solutions through 2034.
Get Full PDF Sample Copy of Report: (Including Full TOC, List of Tables & Figures, Chart) @ https://www.maximizemarketresearch.com/request-sample/221915/
The Global Water Electrolysis Market is entering a more commercial phase as low-emissions hydrogen demand, renewable energy integration, and industrial decarbonization drive investment in electrolyzer projects. Manufacturers are focusing on lower costs, higher efficiency, better durability, and larger system capacities. At the same time, regional manufacturing, PEM and alkaline technology advances, and large-scale hydrogen projects are reshaping the competitive landscape. Maximize Market Research highlights the key trends expected to shape the market through 2034.
Scope of the Water Electrolysis Market Report
Rising Demand for Low-Emissions Hydrogen Drives the Water Electrolysis Market
Water electrolysis uses electricity to split water into hydrogen and oxygen through an electrolyzer. It is a key route to low-emissions hydrogen when powered by renewable or nuclear electricity. Global hydrogen demand surpassed 100 million tonnes in 2025, yet low-emissions hydrogen production reached only almost 1 million tonnes, roughly 1% of the total. This leaves substantial room for electrolysis-based supply to expand, and production is expected to record strong growth in 2026.
Demand is established in refining, ammonia and methanol, and is building in green steel, sustainable fuels, power generation, energy storage and heavy transport. Buyers include hydrogen producers, refineries, chemical and fertilizer companies, steel manufacturers, utilities, renewable-energy developers and industrial gas companies.
Key Highlights & Insights - Water Electrolysis Market
- Installed capacity more than doubled: Global installed electrolysis capacity rose above 4 GW in 2025, with more than 2.5 GW under construction and targeting operation in 2026.
- Investment nearly doubled: Capital spending on low-emissions hydrogen projects reached nearly USD 7 billion in 2025, almost double the 2024 level, with electrolysis-based projects attracting the larger share.
- Manufacturing capacity is far ahead of demand: Global electrolyzer manufacturing capacity reached nearly 38 GW per year in 2024, up 40% year on year, while actual production was only around 4 GW, implying utilization of roughly 10%.
- Large project pipeline: Around 26 GW of electrolysis capacity had reached final investment decision or was under construction with planned operation by 2030.
- Pipeline at risk: More than 100 GW of announced capacity could miss the 2030 operating target if investment decisions are not secured before the end of 2027.
- Production is expanding: Low-emissions hydrogen production reached almost 1 million tonnes in 2025.
Get Insightful Data on Regions, Market Segments, Customer Landscape, and Top Companies (Charts, Tables, Figures and More) https://www.maximizemarketresearch.com/request-sample/221915/
Market Segmentation Insights
- By Technology Type: Alkaline electrolysis is the largest segment because of its commercial maturity, relatively lower capital requirements, proven reliability and suitability for steady, large-scale production. PEM electrolysis is expected to grow faster, driven by its compact design, rapid response and compatibility with variable solar and wind power. Solid oxide electrolysis targets higher efficiency where high-temperature heat is available, while anion exchange membrane (AEM) electrolyzers aim to combine alkaline and PEM advantages with reduced dependence on expensive catalyst materials.
- By Application: Industrial feedstock, including ammonia, methanol and petroleum refining, is the largest application segment. Power generation and energy storage, and power-to-gas, are gaining importance, while transportation, including fuel-cell vehicles and hydrogen refueling, is highlighted as an application with strong growth potential.
- By Capacity and End Use: The report segments the Water Electrolysis Market by capacity, covering systems below 500 kW, 500 kW–2 MW, and above 2 MW, reflecting differences in project scale and hydrogen production requirements. It also analyzes end-use industries, including chemicals, power generation, oil & gas, steel and petroleum, and transportation, highlighting how electrolyzers are being adopted for hydrogen production, industrial feedstock, energy storage, refining, and low-carbon fuel applications.
- By Region : The report segments the Water Electrolysis Market by region covering North America; Europe; Asia Pacific; Middle East & Africa; South America
Regional Analysis:
Asia-Pacific Leads the Global Water Electrolysis Market as China Accounts for Nearly Three-Quarters of New Installations in 2025
Asia-Pacific leads the market on strong manufacturing, large industrial hydrogen demand and government-backed programs. China accounted for nearly three-quarters of new electrolysis installations in 2025 and holds close to 60% of global electrolyzer manufacturing capacity. India is emerging as an important market, with a focus on green hydrogen for refining and fertilizers. Japan and South Korea are developing hydrogen for power generation and fuels, Australia is advancing large renewable-hydrogen projects, and Indonesia, Malaysia and Vietnam are targeting ammonia, methanol and steel.
Europe is driven by decarbonization policy, including the EU's target of 40 GW of domestic electrolyzer capacity by 2030. More than 2 GW of European electrolysis projects reached final investment decision between September 2023 and August 2024. Germany, Spain, the Netherlands and France are leading project development across refining, chemicals, steel and renewable integration. The IEA expects much of the near-term additional capacity to come from Europe.
North America is advancing through hydrogen hubs, industrial decarbonization programs and financial incentives, with demand potential from refining, chemicals, steel and transportation. Canada is developing clean hydrogen using its low-carbon electricity.
Middle East & Africa is focused on very large export-oriented projects. Saudi Arabia's NEOM Green Hydrogen Project targets approximately 2.2 GW of electrolyzer capacity by 2027, and Oman, the UAE and Egypt are also developing projects.
South America, led by Chile and Brazil, offers long-term potential based on strong renewable resources, though many projects remain at the development stage.
Challenges to Watch
High electrolyzer costs, electricity requirements, project delays, financing constraints and uncertain hydrogen offtake are slowing commercial deployment.